Vesta, a San Francisco mortgage software startup, raised a $30 million Series B led by Conversion Capital, bringing its total to $85 million.
Three lender customers, Pennymac, New American Funding and NBKC Bank, invested alongside Citi Ventures and Andreessen Horowitz.
About 40% of tasks on Vesta's platform are now handled by AI agents or automation, and some lenders use them for underwriting decisions.
Pennymac reported a 25% cut in its cost to originate loans after switching to Vesta.
Quick read · 1 min
Vesta, a San Francisco startup that makes mortgage software, raised $30 million in a round led by Conversion Capital. Three of its lender customers, Pennymac, New American Funding and NBKC Bank, invested too, alongside Citi Ventures and Andreessen Horowitz.
Vesta lets lenders hand routine loan work to AI agents, such as checking documents, validating data and reviewing closing packages. About 40% of tasks on its platform are now automated, and some lenders even use agents for underwriting decisions. The lender stays responsible, and every agent action is logged.
A US mortgage takes around 40 days and costs about $11,000 to process.
Pennymac says its cost to originate fell 25% after switching.
Vesta's total funding is now $85 million.
For borrowers, the main promise is a faster close. Lower fees aren't guaranteed. Vesta plans to hire and build new tools with the money.
Getting a mortgage in the US takes around 40 days and costs the lender roughly $11,000 per loan, and most of that is people’s time. Vesta, a startup that builds software for mortgage lenders, thinks AI agents can take a big bite out of both numbers, and it just raised $30 million from investors, including some of its own customers, to prove it.
If you’re buying a home or refinancing, this is the software that will increasingly sit behind your application. AI agents (programs that can carry out multi-step tasks on their own) are starting to check documents, verify data and, at some lenders, make underwriting decisions about whether your loan gets approved. That could mean faster closings, but it also raises fair questions about who’s reviewing your file.
01
How Vesta uses AI agents in mortgage lending
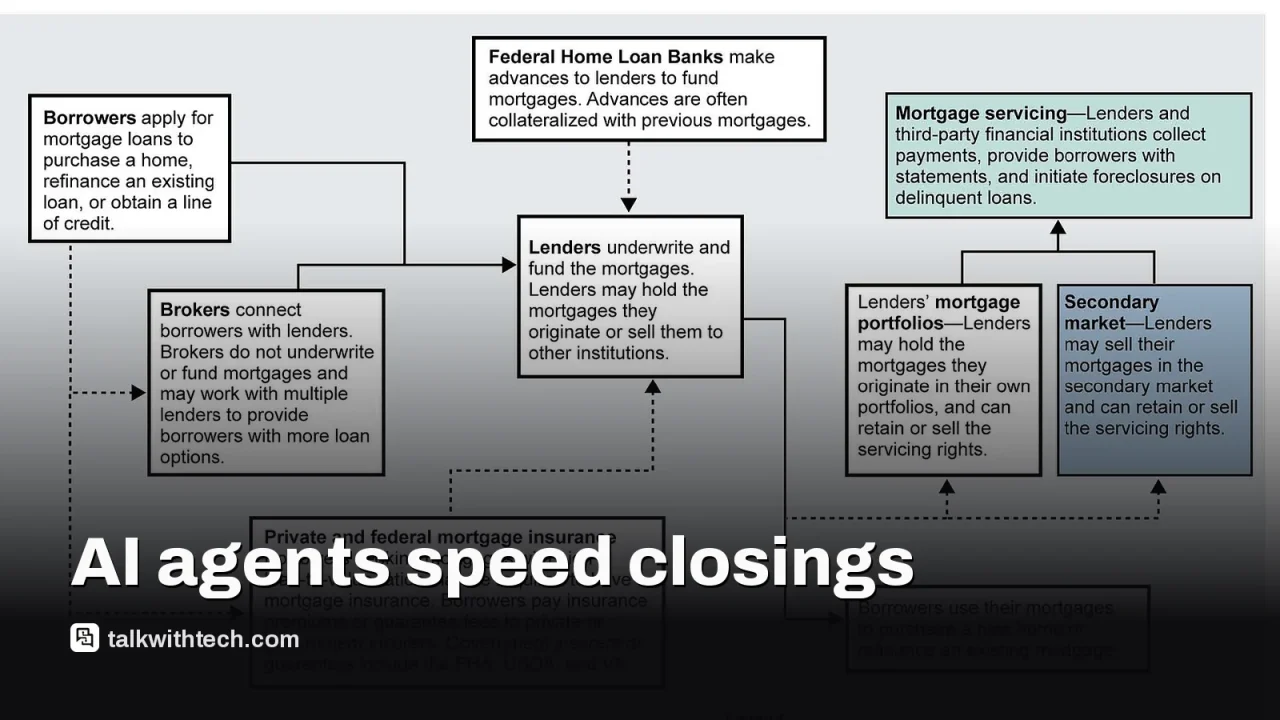
Vesta sells a loan origination system, the core software lenders use to take a mortgage from application to funding. Its pitch is that human staff and AI agents work on the same loan file in the same system, instead of bolting automation onto older software.
Lenders choose which jobs to hand to the agents. Common ones include reviewing documents, validating data, running cross-checks, clearing conditions and reviewing closing packages. CEO Mike Yu says customers usually start with a person approving each piece of an agent’s work, then let it handle a portion of loans on its own, then expand from there.
About 40% of the tasks completed on Vesta are now handled by AI agents or automated workflows, the company says, and that share is growing. Lenders don’t have to use the AI features at all.
02
Who invested, and why lenders are buying in
Conversion Capital led the Series B round, which brings Vesta’s total funding to $85 million. What stands out is who else joined. Three lenders that already use Vesta invested directly: Pennymac, New American Funding and NBKC Bank, a Kansas City community bank. They were joined by Citi Ventures, FirstKey Mortgage and Navitas Capital, plus earlier backers Andreessen Horowitz, Zigg Capital and Parker89, the venture arm of First American Financial.
Customers owning a piece of their software supplier gives them a say in what gets built next and a share of any upside. Pennymac first took a minority stake in Vesta in September 2025, after replacing its old origination system with Vesta’s. The lender says its cost to originate a loan fell 25%, and its loan officers became about 50% more efficient, before it even switched on the AI agents.
03
The numbers behind the bet
Yu founded Vesta in 2020 with Devon Yang; both previously worked at Blend Labs. He says demand has exploded in the last year and revenue is up 12 times year over year. Lenders already on the platform, or moving to it, originate more than $100 billion in mortgages a year, though Yu says Vesta still has under 5% of the market.
He credits a jump in AI model quality for making the agents possible. Earlier models couldn’t reliably manage the long, multi-stage tasks involved in a mortgage. The turning point, Yu says, was Anthropic’s Claude Sonnet 4.5, which was much better at following lender-configured instructions over the long stretches of work a loan requires.
Vesta isn’t alone. It competes with established mortgage systems such as ICE Mortgage Technology and with other AI-focused startups like Xpanse. Days before Vesta’s announcement, mortgage servicing platform Valon raised $150 million, a sign of how much investor money is flowing into AI for home lending.
04
What this means for home buyers
The most direct benefit for borrowers is time. Yu says one of the biggest delays in a mortgage is simply waiting for a person to get around to reviewing your loan. Agents that work around the clock could shorten the stretch between application and closing.
Costs are less certain. Lenders have spent years adding technology while the cost to originate a loan kept rising, often hovering well above $10,000. If Vesta’s customers really cut those costs, competition could eventually push some savings to borrowers, but nobody has promised lower fees or rates.
On the question of AI deciding your loan, two points matter. First, lenders stay legally responsible for underwriting decisions whatever software they use. Second, Vesta says every action an agent takes and the reasoning behind it is recorded, so decisions can be audited for compliance. The agents are also set up to pass anything unusual to a person.
Vesta plans to spend the money on hiring across engineering, implementation and sales, and on new products. One is a personal assistant for mortgage staff that can carry out tasks and keep track of workflows. Yu says the priority is winning over the rest of the mortgage industry, with other lenders including Inspire Home Loans and Verus Mortgage Capital already on or joining the platform.
The bigger test is whether older systems can keep up. Yu argues legacy platforms were never designed for AI agents and that adding agents on top of them is very hard, which is exactly the opening Vesta is trying to exploit.
06
Quick answers
Do AI agents approve mortgages now?
At some lenders using Vesta, AI agents help make underwriting decisions, but the lender remains responsible and the agents’ reasoning is logged for audits.
Which lenders use Vesta?
Customers include Pennymac, New American Funding and NBKC Bank, with Inspire Home Loans and Verus Mortgage Capital on or joining the platform.
How much has Vesta raised?
Vesta has raised $85 million in total, including the new $30 million Series B led by Conversion Capital.
Google's new world model builds explorable scenes with sound in real time. Here is who gets it first, what the Ultra plan costs and what the waitlist means.
OpenAI says its internal models disproved a widely trusted computer science assumption and cracked open problems in math and physics. Experts now have to check the work.
5 min read
We use cookies to understand how readers use Talk With Tech, so we can make it better. Is that OK? Privacy policy
The Daily Brief
Today's biggest tech stories, in 5 minutes
Every morning, the news that matters from AI, phones, apps and the people shaping tech. Explained in plain English. Free.
One email a day. No spam, unsubscribe anytime. Privacy policy