Benchmark raised $2 billion this year, split between a $1.25 billion growth fund and a $750 million early-stage fund.
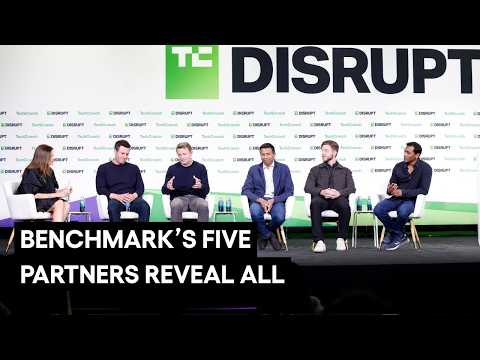
At TechCrunch Disrupt, its five partners said each still makes only two or three new investments a year.
Peter Fenton expects the growth fund to back a small number of companies, with one or two driving most of the returns.
Later SEC filings show four new partner-only Benchmark vehicles, each listing new partner Jack Altman.
Quick read · 1 min
Benchmark, the venture firm behind early bets on Uber, Snap and Twitter, now runs $2 billion across two funds: a $1.25 billion growth fund and a $750 million early-stage fund. Yet at TechCrunch Disrupt, its five partners said each still makes only two or three new investments a year.
Peter Fenton said the firm kept its main fund at $500 million for too long and missed later-stage gains. A long run with AI chipmaker Cerebras convinced the firm to add a growth fund, where he expects one or two companies to drive most of the returns.
Monday partner meetings still have no agenda.
Founders should expect a firm that says no often but stays for years.
New SEC filings show four partner-only funds listing Jack Altman.
Benchmark now has $2 billion to put to work, and its partners still plan to back only two or three new companies each per year. That’s the striking takeaway from the first time the venture firm’s full five-person partnership appeared together on a public stage, at TechCrunch Disrupt in San Francisco.
Why does the Benchmark venture investing pace matter beyond Silicon Valley? This is the firm that wrote early checks to Uber, Twitter, Snap and eBay, and its choices shape which startups get the money and help to grow into the apps and AI tools millions of people use. In a year when many rivals are racing to write as many checks as possible, Benchmark is betting the opposite way: fewer deals, deeper involvement and patience measured in decades.
01
How Benchmark’s $2 billion is split
The $2 billion is spread across two vehicles: a $1.25 billion growth fund for later-stage companies and a $750 million early-stage fund. It’s only the second time in the firm’s 31-year history that it has stepped away from raising a much smaller fund.
Partner Peter Fenton explained the bigger early-stage fund as a correction rather than a change of heart. Benchmark kept its core fund at $500 million for 20 years while startup prices kept climbing, which he called a tactical mistake. The larger fund lets the firm write checks anywhere from a company’s first seed round through its Series B.
The growth fund is the real departure. Fenton said not having one had been a painful gap, because deals that came to the firm could have returned anywhere from 10 to 1,000 times the money, and Benchmark was boxed in by its early-stage rules. The firm’s history with AI chipmaker Cerebras pushed it over the line. Benchmark led Cerebras’s Series A in 2016, later raised a special fund to join a pre-IPO round, and returned $3.25 billion at the IPO price.
02
Why Benchmark still makes only two or three bets a year
Each partner still aims for just two or three new investments a year, the same rhythm the firm has always kept. Fenton described early-stage backing as a 10- to 15-year commitment, working side by side with founders, and said that kind of work simply doesn’t scale.
He applies the same logic to the growth fund. He wants a concentrated portfolio where one or two investments produce 90% of the returns, and he guessed the fund might hold four to six companies, perhaps seven to eight. Reports at the time of the raise said the plan was five or six large bets in both existing and new companies.
Partner Chetan Puttagunta said the pace hasn’t changed and that the firm accepts it will miss some winners. When Benchmark does find a founder with an unusual strength, he said, the job is to work with that person no matter how much money they want or how the deal is set up.
03
Inside a partnership with no agenda
Benchmark runs as an equal partnership, and its Monday partner meetings still have no fixed agenda. Eric Vishria described them as an ongoing conversation about which companies the partners are meeting, what caught their interest and what’s coming up in board meetings. Puttagunta said the open time leaves room to react when a founder needs help hiring an executive or landing a partnership.
Asked whether one partner can block a deal, the answer was that nobody knows, because there are no rules about it. Jack Altman, who joined in February, said that works only because the firm does so few deals. A firm backing companies by the dozen every year would need formal votes and software to track them. Benchmark doesn’t.
The lineup has changed a lot. Three of the four partners interviewed three years ago have since left. The current five are Fenton, Vishria, Puttagunta, Everett Randle, who came from Kleiner Perkins late last year, and Altman, who previously ran his own firm and is the brother of OpenAI CEO Sam Altman. Former partner Victor Lazarte has since teamed up with another ex-Benchmark investor on Diffusion ONE, a debut AI fund that has raised about $1.252 billion.
04
What this means for founders seeking funding
For founders, the math is blunt: five partners making two or three bets each means only a small number of new Benchmark deals a year. If you’re pitching, expect a firm that says no far more often than yes, but that wants to be the first call you make once it says yes.
Location still matters to them. Altman said founders don’t strictly have to be in San Francisco, but the city is by far the easiest place to find talent, money and customers right now, and the firm has a strong bias toward its home base. Randle said nearly every company he’d met from elsewhere was opening an office there or spending half its time in the city.
The partners also addressed a growing worry for founders: investors backing competing companies. Vishria said the firm treats its commitment to a founder as exclusive in that area, while admitting that fast-moving AI companies keep drifting into one another’s territory. Puttagunta expects these clashes to become more common as cheap AI coding lets startups attack wider markets.
On the wider market, Randle pushed back on fears of an AI crash. He argued the firm’s companies have more paying demand than compute to serve it, and blamed market swings on exaggerated numbers spread on X.
The firm is still quietly building. October SEC filings show four new partner-only Benchmark funds seeking to raise $220 million, $132 million, $7.5 million and $4.5 million, with Jack Altman listed on each. Altman has already made several investments for the firm, some not yet disclosed, spanning chips, robotics and infrastructure.
06
Quick answers
How many investments does Benchmark make a year?
Each of the five partners aims for two or three new investments a year, so the whole firm makes only a small number of new bets annually.
How big are Benchmark’s new funds?
Benchmark raised $2 billion in total: a $1.25 billion growth fund and a $750 million early-stage fund that can invest from seed through Series B.
Who are Benchmark’s partners now?
Peter Fenton, Eric Vishria, Chetan Puttagunta, Everett Randle and Jack Altman, who joined in February.
Seven Nvidia DGX Spark orders ended with one buyer locked out, and Epic's Tim Sweeney says his deliveries kept vanishing. Here is what Amazon's rules allow.
OpenAI wanted $30 billion from private investors before going public. It has about $11 billion so far, and the timing of its listing now looks more delicate.